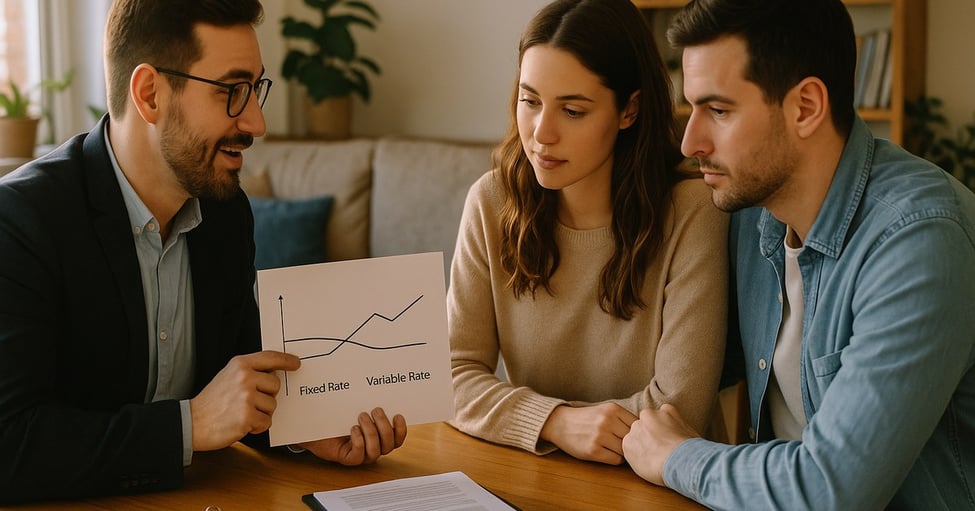
Variable rates are showing up in mortgage conversations again, and there is a reason for that.
That does not mean everyone should take one. It means borrowers should understand why a broker may bring up variable rates sooner than a bank branch does.
Robert McLister, writing in the Financial Post, recently looked at why brokers tend to recommend variable-rate mortgages more often than banks. His point was not that variable is always better. It was that brokers are usually comparing more lenders, looking at qualification from more angles, and paying closer attention to penalties if a borrower needs to break the mortgage early.
For anyone buying, renewing, or refinancing, those details can matter just as much as the rate itself.
Brokers See More Than One Lender

One of the biggest differences between a bank and a broker is choice.
A bank can offer its own mortgage products. A broker can compare options across multiple lenders, including banks, monoline lenders, credit unions, and other lenders depending on the file.
That matters because lenders are not all competitive in the same place at the same time. One lender may have a strong 5-year fixed rate. Another may be better on variable. Another may be more flexible for someone who is self-employed, buying with less than 20 per cent down, or renewing under pressure.
McLister pointed to data from DLCG Mortgage Group showing that, through mid-June, 56.8 per cent of prime applicants in that broker network were choosing floating-rate mortgages. By comparison, April bank data showed a much lower variable-rate share for new bank mortgages.
That does not automatically mean brokers are right and banks are wrong. It does mean borrowers may hear a different conversation depending on where they start.
Qualification Can Change the Discussion

This is the part a lot of people miss.
The mortgage stress test does not only look at your actual payment. Lenders qualify you at the higher of your contract rate plus two percentage points, or the required minimum qualifying rate.
So when variable rates are lower than fixed rates, they can sometimes help a borrower qualify for more. McLister noted that floating rates were running about 55 basis points below fixed rates at the time of his article. On the same income, that could translate into roughly five per cent more borrowing capacity.
In Mississauga, Toronto, Brampton, Oakville, and other GTA markets, five per cent can change the conversation.
But this is where advice matters. Qualifying for more does not mean you should automatically borrow more. A lower starting rate can help with approval, but you still need to be comfortable if payments rise later.
We always want to separate two questions:
Can you qualify?
And can you live with the payment if things change?
Those are not always the same thing.
Penalties Are a Real Cost
A lot of borrowers focus almost entirely on the rate. That is understandable, but the penalty structure can be just as important.
Variable-rate mortgages usually come with a penalty of three months’ interest if you break the mortgage early. Fixed-rate mortgages can be much more complicated, especially with major banks that use interest rate differential calculations.
Those penalties can be painful if you sell, refinance, separate, move for work, or need to restructure debt before the term ends.
This is one reason brokers may talk about variable rates with younger buyers, people expecting life changes, or homeowners who want flexibility. It is not only about trying to guess where rates go. Sometimes it is about keeping the exit cost manageable.
That said, variable rates come with trade-offs. Payments may move if the Bank of Canada changes rates, depending on the product. Some borrowers are fine with that. Others sleep better with a fixed payment and no surprises.
The right answer depends on the person, not just the spreadsheet.
Banks and Brokers Approach the Conversation Differently
Banks have improved their mortgage advice, and some borrowers get excellent offers by negotiating directly with their bank. Especially at renewal, a strong client with good credit and income may be able to push for a better deal.
But brokers are built differently. Their job is mortgage placement. They are comparing lenders every day, looking at approvals, policy exceptions, penalties, rate trends, and file structure.
That is why the conversation should go beyond, “Here is the lowest rate.”
For example, if you are self-employed, which lender will treat your income fairly? If you are renewing, should you stay, switch, or restructure? If you may move in two years, does a low fixed rate still make sense if the penalty could be large?
Those are practical questions. They can save money, stress, or both.
Variable Is Not a Personality Test
Some people talk about fixed versus variable like one side is smart and the other is scared. That is not helpful.
A variable rate can make sense for a borrower with stable income, a strong emergency fund, and comfort with payment movement. It may also make sense if the spread between variable and fixed is wide enough to justify the risk.
A fixed rate can make sense for someone with a tighter monthly budget, a young family, or no interest in watching Bank of Canada announcements. Predictability has value too.
The better question is not, “Which one is best?”
The better question is, “Which one fits your numbers, your timeline, and your tolerance for change?”
That is where a proper mortgage review helps. Not a quick rate quote. A full look at income, debts, down payment, term plans, penalties, and what could happen if rates move.
*The takeaway:* variable rates are getting more attention for good reasons, but they are not automatically the right choice. The best mortgage is the one that fits the borrower, not the one that sounds best in a headline.