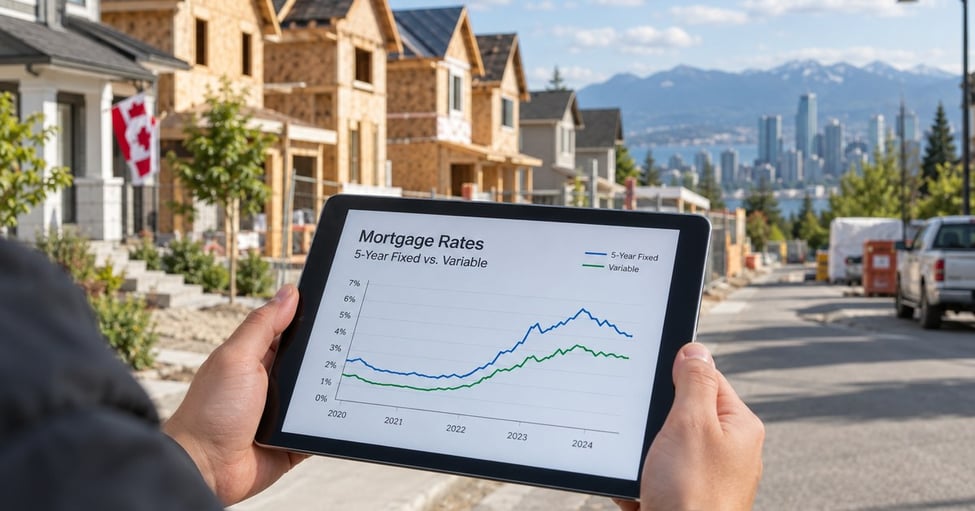
A senior Bank of Canada official said something this week that is worth paying attention to if you are buying, renewing, selling, or just trying to make sense of housing in Canada.
According to a Canadian Press report published by BNN Bloomberg, senior deputy governor Carolyn Rogers told a business audience in Victoria that the Bank of Canada’s policy rate is not built to solve housing affordability on its own.
That may sound obvious, but it matters. A lot of people look at housing through one question: when will rates come down?
Rates matter, of course. They affect mortgage payments, qualification, buyer confidence, and prices. But they are only one part of the problem.
One Interest Rate Has to Cover the Whole Country

The Bank of Canada sets one policy rate for the entire economy. It does not get to set one rate for condos in Toronto, another for detached homes in Mississauga, and another for business loans in Alberta.
That is the issue Rogers was pointing to. Housing markets across Canada are not all dealing with the same problem at the same time.
Some cities need more supply. Some are dealing with weaker demand. Some have zoning and permit delays. Some are still expensive even after prices have softened. A single interest rate has to touch all of that, plus inflation, employment, consumer spending, business investment, and the broader economy.
That makes the policy rate powerful, but not precise.
When rates fall, borrowing gets easier and monthly payments can look better. But if supply is still tight, lower rates can push more buyers into the same limited pool of homes, which can move prices higher again.
When rates rise, demand cools and prices may ease. But buyers also qualify for less, monthly payments climb, and people who might otherwise enter the market get pushed back to the sidelines.
That is the blunt instrument problem.
Housing Has Become Too Central to the Economy

One of the more interesting points in the report was how much Canada’s economy has shifted toward housing.
Rogers noted that in 2000, residential investment made up 4.3 per cent of Canada’s GDP, while business investment in machinery and equipment was 8.3 per cent. Today, those roles have largely flipped.
That is a big deal.
When housing takes up that much space in the economy, every policy choice gets harder. Falling prices may help some buyers, but if prices fall too far for too long, homeowners feel less wealthy, construction can slow, and related jobs can be affected.
At the same time, if prices keep rising faster than incomes, younger buyers, newcomers, and renters trying to move into ownership fall further behind.
So we are stuck with a difficult balance. Canada needs homes to be more affordable, but the country has also built a lot of household wealth, lending activity, and economic confidence around rising home values.
That is not something the Bank of Canada can unwind by itself.
Stability Rules Can Make Buying Harder

The article also raised an important point about mortgage regulation.
Rules like the mortgage stress test were designed to protect the system. They force borrowers to qualify at a higher rate than the contract rate, which helps make sure people can handle payment shocks.
That stability matters. We do not want a housing market where people are approved at the absolute edge of affordability with no room for rates, income, or life to change.
But there is a trade-off. Those same rules can make it harder for first-time buyers to qualify, especially in expensive markets.
This is where the conversation gets uncomfortable. A rule can be good for financial stability and still make access harder for real buyers. Both things can be true.
We see this all the time in mortgage conversations. A buyer may have a strong job, good savings, and a realistic plan, but the qualifying rate can still limit what they can purchase. That does not mean the rule is pointless. It means buyers need to understand the rules early, not after they have already fallen in love with a property.
Why Inflation and Mortgage Costs Feel Confusing
Rogers also touched on something many homeowners find frustrating: higher interest rates are meant to cool inflation, but higher mortgage interest costs also show up in shelter inflation data.
So from a homeowner’s point of view, it can feel backwards.
The Bank raises rates to fight inflation. Then mortgage payments rise. Then shelter costs look higher. No wonder people get confused.
The missing piece is timing. Higher rates can add pressure to mortgage costs right away, especially for variable-rate borrowers or people renewing. But over time, higher borrowing costs are supposed to cool demand across the economy, which can reduce broader inflation pressure.
That explanation does not make the payment easier. But it does explain why the headline inflation number and the household budget can feel like they are telling different stories.
What This Means for Buyers and Homeowners
If you are waiting for the Bank of Canada to “fix” affordability, you may be waiting for the wrong thing.
Rate cuts can improve cash flow and qualification. They can also bring more buyers back into the market. If supply has not improved, that extra demand can put upward pressure on prices again.
For buyers, the better question is not simply, “When will rates drop?”
The better questions are:
Can I afford the payment today?
What happens if rates are different at renewal?
Am I buying with enough room in my budget?
Is this property still workable if condo fees, taxes, or maintenance costs rise?
For homeowners renewing, the same logic applies. Do not build your plan around headlines. Build it around your actual mortgage balance, income, payment comfort, and timeline.
For sellers, this is a reminder that affordability is not just about price. Buyers are looking at monthly cost, qualification, taxes, insurance, and risk. A list price that made sense in a lower-rate market may not feel the same to a buyer using today’s math.
The Real Fix Needs More Than Rates
The Canadian Press report makes one thing clear: housing affordability needs more than monetary policy.
Rates can influence demand, but they cannot approve permits, build infrastructure, change zoning, add skilled labour, or decide where new homes should go.
That work sits with governments, regulators, builders, lenders, and the private sector. It also takes time, which is not always what people want to hear.
In the meantime, households still have decisions to make. People still need to buy, sell, renew, refinance, separate, relocate, and plan for the next stage of life.
That is why the practical work matters. Know your numbers. Stress-test your own budget. Understand the mortgage options before you need them. Do not assume a rate cut will solve a purchase that is already too tight.
*The takeaway:* interest rates matter, but they are not a housing plan. Affordability will only improve in a lasting way when borrowing costs, supply, regulation, and household budgets are all part of the conversation.